THE TRUST TEST
The challenge is to demonstrate that the lessons of recent incidents lead to lasting improvements…
Every banking transaction begins with an act of faith. Depositors expect savings to be secure, businesses rely on payments reaching their destination and borrowers trust institutions to act responsibly.
Behind the technology, financial statements and regulatory safeguards lies a relationship that can take decades to build – and a single incident to unsettle.
Recent revelations of financial fraud in Sri Lanka have brought that relationship into sharper focus. Disclosures of internal wrongdoing, alongside the continuing threat of online scams and impersonation, raise questions that extend beyond the institutions directly affected.
How effectively are controls monitored and enforced? How quickly can irregularities be detected? And when something goes wrong, how clearly and responsibly do banks respond?
These questions carry particular weight as banking becomes increasingly digital. Faster payments and mobile applications offer considerable benefits but also demand safeguards that evolve alongside them.
For customers, confidence depends on knowing that convenience is supported by protection and help will be available when it’s needed.
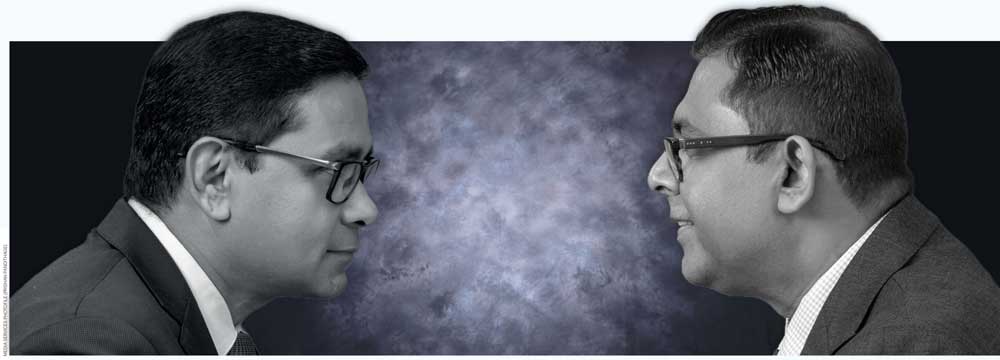
Against this backdrop, Commercial Bank of Ceylon’s (ComBank) Managing Director and Chief Executive Officer Sanath Manatunge, and Hatton National Bank’s (HNB) Managing Director and Chief Executive Officer Damith Pallewatte, provide complementary perspectives to this month’s cover story.
Their observations examine the responsibilities of banking leadership at a time when institutional resilience and public confidence are being closely scrutinised.
For Manatunge, trust is shared across the banking sector: An incident at one institution can influence perceptions of others, making collective vigilance, timely communication and cooperation essential.
Behind the technology, financial statements and regulatory safeguards lies a relationship that can take decades to build – and a single incident to unsettle
Pallewatte directs attention to the distance between having a control and knowing that it works under pressure. Drawing on his background in risk management, he highlights the importance of independent oversight, clear ownership and an organisational culture in which employees can raise uncomfortable concerns.
Together, their responses underline the breadth of banks’ obligations. Protecting customers requires investment in secure systems, rigorous checks on accounts and transactions, scrutiny of external partners, and prompt cooperation when suspicious funds move between institutions.
It also calls for boards that challenge assurances and management teams that are prepared to test their own assumptions.
For Sri Lanka’s banks, the challenge is to demonstrate that the lessons of recent incidents lead to lasting improvements. Confidence grows when safeguards withstand scrutiny, disclosures are candid and accountability is visible.
So as Manatunge and Pallewatte assert, protecting trust requires sustained action across institutions, leadership teams and the wider financial ecosystem.
– Compiled by Tamara Rebeira