STANDARD CHARTERED SRI LANKA
Q: How has the role of finance evolved within organisations and what does this mean for financial leadership today?
A: Finance has evolved from being primarily a reporting and control function to becoming an integral part of strategic decision making.
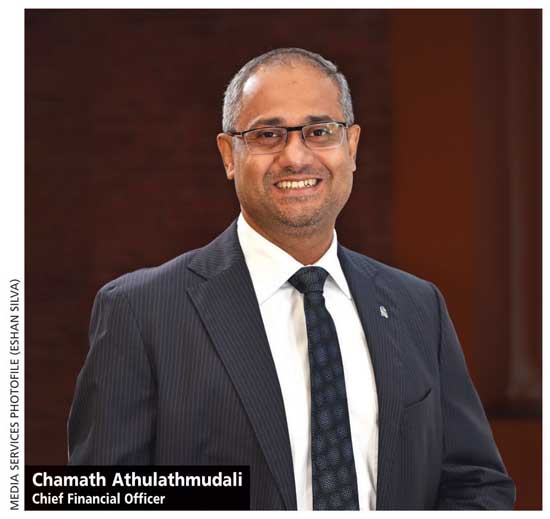
While stewardship, accuracy and governance remain fundamental, finance leaders are increasingly expected to guide resource allocation, evaluate risk adjusted opportunities, and help organisations navigate economic and regulatory uncertainties.
Effective financial leadership therefore requires a balance of commercial understanding, independent challenge and long-term discipline. It is about ensuring that growth ambitions are supported by a resilient balance sheet, sound governance and a clear understanding of risk, while providing the insight needed to make better business decisions and optimise shareholders returns.
Q: What guides your decisions on balance sheet optimisation, particularly when commercial ambitions compete with the need to preserve financial resilience?
A: My approach to balance sheet optimisation is guided by a simple principle: profitability is sustainable only when underpinned by resilience. Commercial growth matters but the balance sheet must also absorb shocks, maintain depositor and regulatory confidence, and preserve the capacity to support clients across economic cycles.
When these priorities compete, three questions are considered.
First, does the opportunity generate economic value after accounting for the capital, liquidity and funding it consumes? Risk adjusted returns are assessed rather than headline revenue as growth that uses disproportionate amounts of scarce resources may be less attractive than it appears.
Second, how will the decision affect our resilience under stress? Its impact on capital ratios, liquidity buffers, funding concentrations and overall balance sheet flexibility is considered.
Third, what future flexibility are we preserving? In banking, growth is often limited not by demand but balance sheet capacity. Therefore, capital and liquidity are allocated to opportunities that offer the greatest long-term strategic value, rather than simply the highest immediate revenue.
My experience has shown that strong financial leadership is not defined by achieving the highest returns in favourable conditions but delivering consistently attractive returns while preserving resilience through uncertainty.
Q: How do you assess whether profitability improvements are sustainable and which performance indicators do you consider most revealing?
A: Sustainability is assessed by asking whether today’s profits can be repeated through the cycle without increasing risk disproportionately. Most revealing indicators are return on tangible equity (RoTE), risk adjusted returns, cost to income ratio (CIR), credit costs, and capital and liquidity metrics.
Strong profitability should be supported by quality revenues, disciplined cost management, efficient use of capital and a resilient balance sheet. If earnings improve while resilience weakens, those profits are viewed as lower quality and potentially unsustainable.
The question is not how much profit we generated this year; it is whether we can generate similar returns through the next economic cycle while maintaining the confidence of regulators, shareholders and clients.
Q: Which financial risks require the greatest attention in your role and how do you ensure that vulnerabilities are identified early?
A: The financial risks demanding the closest attention are capital, liquidity, asset quality and macroeconomic pressures as each directly affects an institution’s resilience and capacity to support clients through the cycle.
At Standard Chartered, vulnerabilities are identified early through forward-looking indicators, rigorous stress testing and strong governance. A culture is promoted in which emerging risks are raised promptly, debated openly and challenged constructively. Drawing on experience and early warning signals, 12-24 month stress scenarios are modelled to uncover vulnerabilities, anticipate shocks and support timely action.
The greatest threats are often not those already visible on the balance sheet but developing beneath the surface. My responsibility is to detect them early enough to act.
Q: What does effective financial governance look like beyond accurate reporting and how do you embed accountability across the organisation?
A: Effective financial governance extends beyond accurate reporting. It provides reliable information, robust controls, clear ownership and accountability across the organisation.
Finance may establish the framework but responsibility for financial outcomes must be shared by the business. Here at Standard Chartered, this is reinforced through clearly assigned metrics, transparent performance reporting, effective governance forums, and a culture in which issues are raised early and challenged constructively.
The true measure of strong financial governance is not how quickly errors are detected but how effectively they are prevented. We as a finance team keep asking ‘why?’ until we fully understand and are satisfied with the answer.
Good financial governance explains what happened; great financial governance ensures that everyone understands their role in achieving the right outcomes from the outset.
Q: What capabilities are you prioritising within your team as finance professionals take on broader strategic and leadership responsibilities?
A: Strategic thinking, business partnering, balance sheet and capital management, data and AI literacy, leadership and sound risk judgement are prioritised at the bank.
Technical finance expertise remains essential but future finance leaders must also influence decisions, allocate resources effectively and translate complex issues into clear action. At Standard Chartered, these capabilities are built through strategic assignments, cross functional collaboration and opportunities for individuals to lead beyond their core responsibilities.
Future finance professionals will be distinguished not by how well they report numbers but how effectively they turn financial insight into better decisions, stronger business outcomes and more resilient organisations.
Q: Where do you see opportunities to improve the banking regulatory framework while maintaining prudential standards and supporting sustainable growth?
A: Regulatory frameworks can become more risk sensitive, proportionate and forward-looking without compromising prudential standards. Greater capital efficiency, streamlined overlapping requirements, responsible adoption of AI, and wider use of stress testing could improve outcomes for both regulators and banks.
The goal should not be lighter regulation but smarter regulation that safeguards resilience and stakeholders, supports sustainable growth and recognises the distinct operating models of international banks. The strongest regulatory frameworks make the banking system safer while preserving its ability to serve the real economy.
In emerging markets, regulation should uphold robust capital and liquidity standards while enabling credit growth, investment, trade and financial inclusion. The challenge is to prevent regulatory requirements from unintentionally limiting banks’ capacity to support economic development, particularly during periods of recovery and expansion.
– Compiled by Tamara Rebeira
COMPANY DETAILS
- Telephone: 2480000
- Website: www.sc.com/lk